Mortgage Advisor in Montgomery, TX
Buying in Montgomery can mean anything from a traditional neighborhood home to a Lake Conroe-area property, a move-up purchase, an investment, or a retirement move. The right financing plan should account for the full picture: payment, taxes, insurance, HOA costs, cash-to-close, and the property itself. I’m Robert Corbell with NEXA Lending, and my approach is Advice First. Financing Second.
We start by understanding what you are trying to accomplish, then compare the financing paths that fit.
Mortgage Planning for Montgomery Buyers
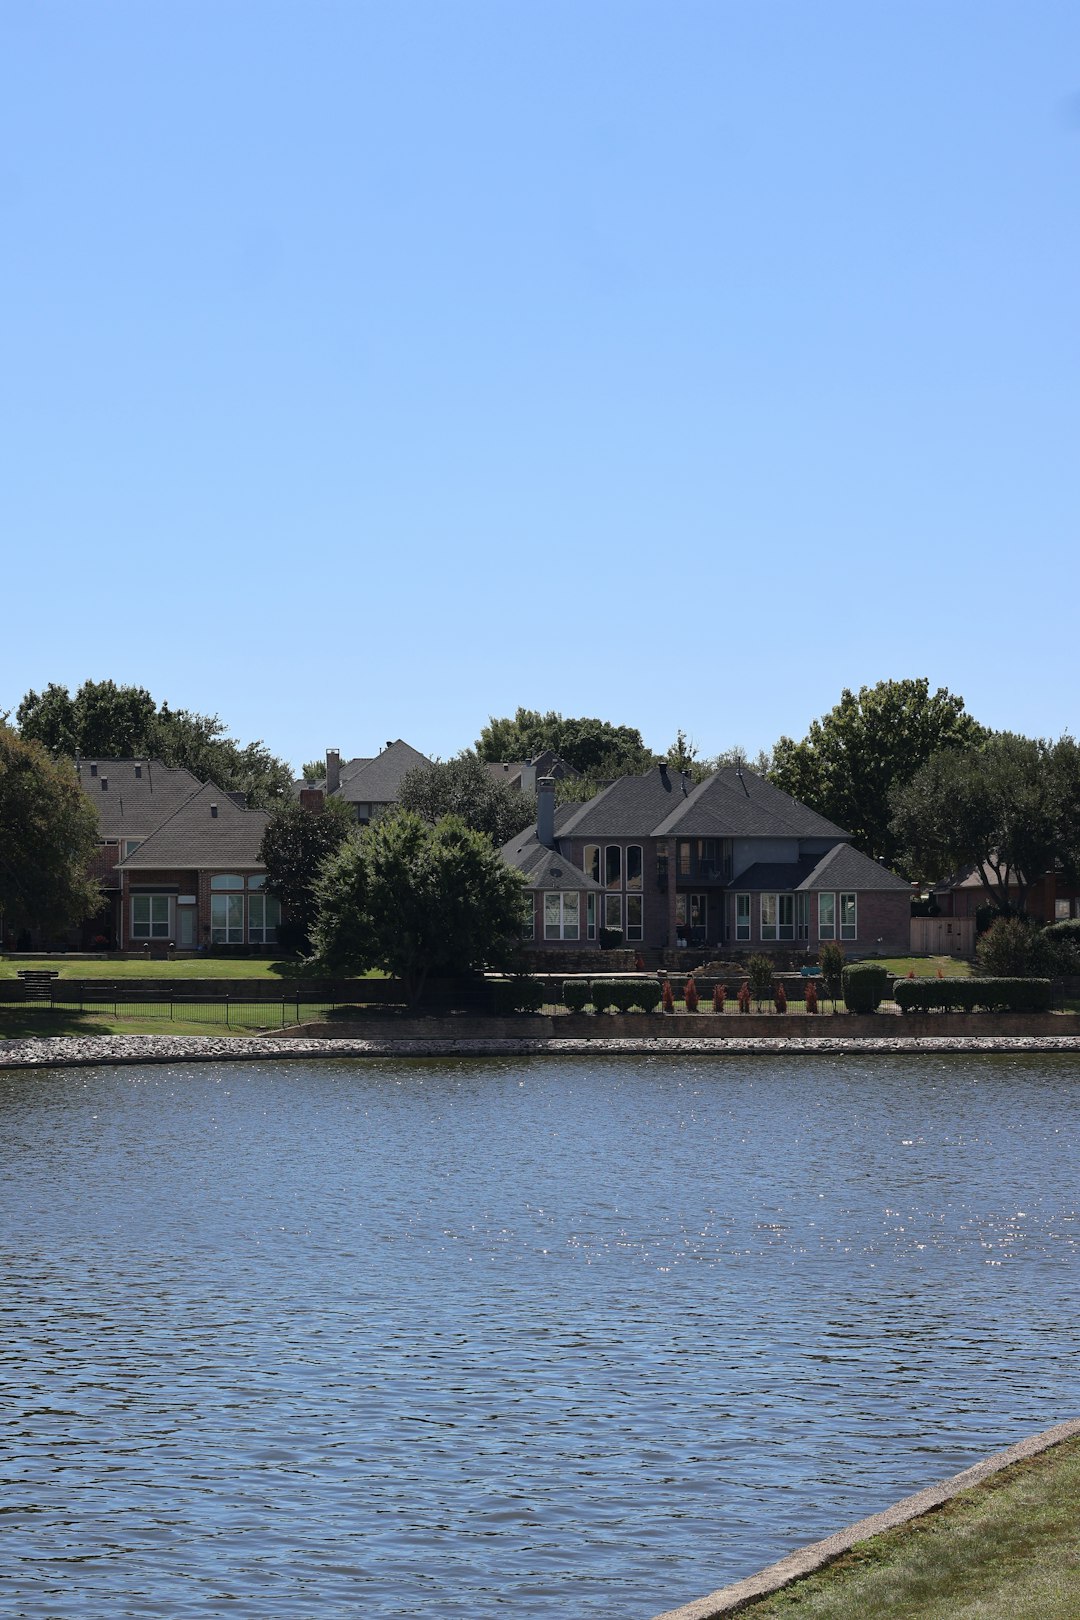
Montgomery buyers may be comparing primary residences, gated communities, homes near the lake, larger properties, retirement moves, or investment opportunities. That makes it important to review the property and the total cost—not just the advertised price.
Financing paths we can compare
- Conventional financing
- FHA loans
- VA loans for eligible veterans and service members
- USDA financing where borrower and property eligibility apply
- Jumbo financing
- Self-employed and bank-statement programs where available
- Second-home financing where applicable
- Investor and DSCR financing
Look at the full housing cost
Depending on the property, your monthly or upfront costs may include taxes, homeowners insurance, flood insurance where applicable, HOA or community dues, mortgage insurance, and reserves in addition to principal and interest.
Lake-Area Properties Need Extra Attention
A property near or on the water can bring additional questions that are worth addressing before you make an offer.
- Insurance and possible flood-zone considerations
- HOA, POA, or community fees
- Property condition and appraisal considerations
- Whether the property will be a primary residence, second home, or investment
- Reserve and cash-to-close planning
The goal is not to make the process complicated. It is to identify important questions early enough to make a sound decision.
Move-Up and Lifestyle Buyers
Montgomery attracts buyers looking for more room, different amenities, or a change in lifestyle. If you are selling another home, we can compare how available equity, down payment, timing, and payment changes affect your next move.
Retirement and Later-Life Moves
A retirement move may be less about maximizing buying power and more about preserving liquidity, controlling monthly housing costs, and deciding how much equity to put into the next home. That calls for planning before financing.
Investment and Second-Home Conversations
If the property is not your primary residence, the financing rules can change. Depending on your plans, we may compare conventional second-home or investment financing, DSCR programs, reserve requirements, down payment, and how expected property use affects eligibility.
If your goal is long-term real estate investing, the mortgage decision should fit the broader strategy—not just this one transaction.
My Mortgage Planning Process
Clarify the property and goal
Primary home, move-up, retirement, second home, or investment—start with the purpose.
Review payment and cash
We estimate payment, closing funds, reserves, and property-specific costs.
Choose the financing path
We compare the programs that fit the borrower and property.
Stay informed through closing
I keep you updated on documentation, underwriting, and next steps.
Serving Montgomery and Nearby Communities
I serve buyers throughout Texas with a strong local focus on Montgomery, Conroe, Magnolia, Willis, The Woodlands, Spring, and surrounding Lake Conroe communities.
You can also visit the Conroe mortgage advisor page, The Woodlands mortgage advisor page, and the relocating to Texas checklist.
Frequently Asked Questions
Can you help with a home near Lake Conroe?
Yes. We can review the financing together with insurance, HOA, property-use, and other property-specific questions that may affect the transaction.
Can a property be financed as a second home?
Possibly. Eligibility depends on how the property will be used and the requirements of the loan program.
Do you offer investor financing?
There may be conventional investment and DSCR options depending on the property and borrower profile.
Can I talk before I am ready to apply?
Yes. A planning conversation is often the best first step.
Start With a Clear Plan
Whether the goal is a primary home, lake lifestyle, retirement move, or investment, the financing should support the bigger picture.
Robert Corbell | NMLS #2142736 | NEXA Lending